Buying a luxury home is not just about selecting the right apartment. It is equally important to understand the funds required at the time of booking, the payments to be made during construction, and the total amount payable before possession.
Understanding the payment plan is particularly crucial for those looking to buy a home at Trump Tower Noida in Sector 94, as this project falls within the ultra-luxury residential segment, where even a small fraction of the property's cost can represent a significant financial commitment.
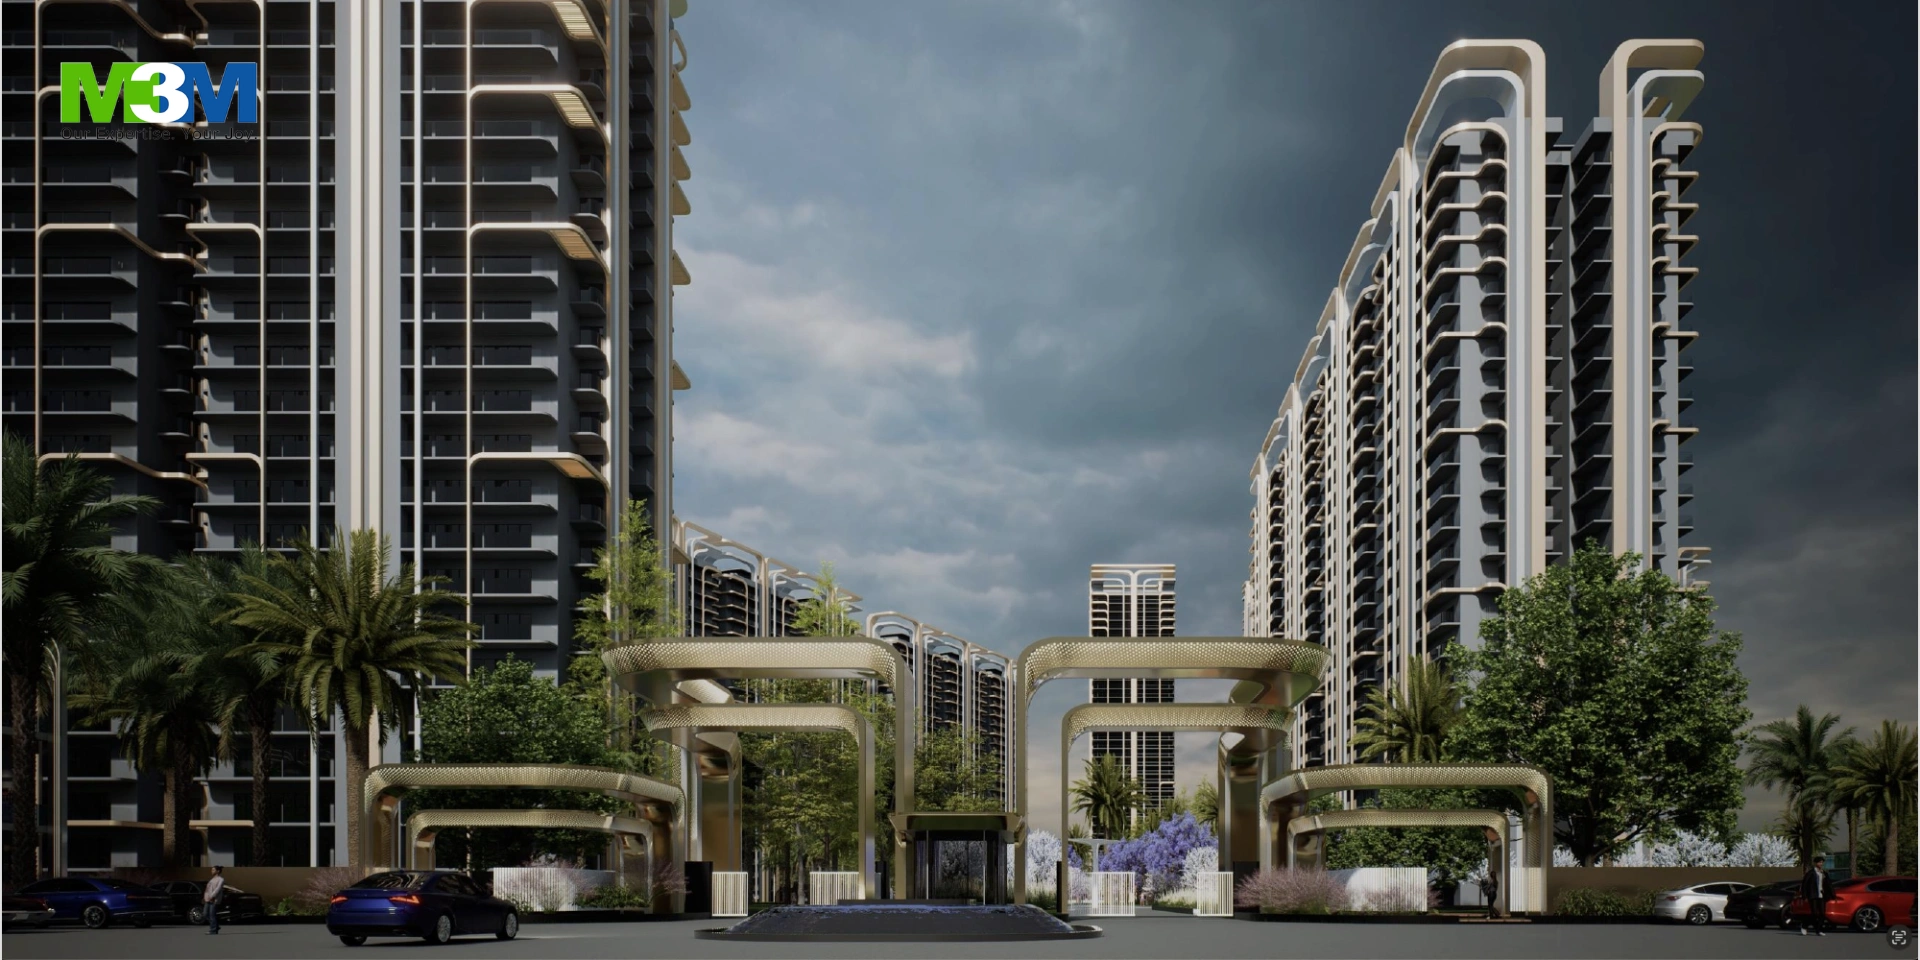
Trump Tower Noida is being marketed as part of 'M3M The Cullinan II', a residential project by 'Lavish Buildmart Private Limited'. The project is registered with UP RERA under registration number UPRERAPRJ794824/10/2025. According to RERA records, the completion date is July 31, 2030. Buyers should verify the project's latest records and documents before making any financial commitments. Source: UP-RERA project record
This guide explains the reported price range, common payment structures, example calculations, additional costs and important checks to complete before booking.
Buyer note: The prices and payment methods mentioned in this article are estimates based on research and do not constitute a formal quotation from the developer. The final payable amount depends on the selected unit, floor, view, applicable charges, prevailing offers, and the signed allotment documents. Always obtain a cost sheet and payment schedule—specific to the date and unit—before transferring any funds.
Particular | Details |
Project marketed as | Trump Tower Noida |
Registered project name | M3M The Cullinan II |
Location | Plot No. 1, Sector 94, Noida, Uttar Pradesh |
Promoter in RERA record | Lavish Buildmart Pvt. Ltd. |
RERA registration number | UPRERAPRJ794824/10/2025 |
RERA registration date | 3 October 2025 |
Declared completion date | 31 July 2030 |
Reported residence sizes | Approximately 4,925 sq. ft. and 5,685 sq. ft. |
Property segment | Ultra-luxury residential |
Payment plan | Confirm the currently applicable plan in writing |
Pricing | Subject to unit, floor, view and current offer |
Important: The registered project name and the marketing name may differ. Verify that the allotment letter, payment receipts and RERA documents refer to the correct phase and promoter.
The price of a home at Trump Tower Noida can vary based on factors such as size, floor, view, layout, premium features, and payment method.
Online property listings show varying estimated rates. Some listings indicate a base rate of approximately ₹35,000 per square foot, while others quote higher rates. These are estimated market rates and should not be considered the developer's official pricing.
To help you estimate an initial budget, the table below uses an estimated price range derived from third-party market listings; this does not represent confirmed inventory or an official price list.
Configuration | Approx. Super Area | Indicative Price Range | Illustrative 10% of Base Price |
4 BHK Standard | 4,925 sq. ft. | ₹17.24 Cr – ₹20.68 Cr | ₹1.72 Cr – ₹2.07 Cr |
4 BHK Double-Height Living | 5,685 sq. ft. | ₹19.90 Cr – ₹23.89 Cr | ₹1.99 Cr – ₹2.39 Cr |
Price references: third-party listings, including NoidaLuxury and Square Yards. Figures are indicative and may not reflect current availability or the final cost sheet.
Please note: The 10% figures above are mathematical illustrations only. They do not confirm that the developer currently accepts 10% as the booking amount. The actual amount due at booking may include additional components and may follow a different schedule.
Why can two buyers receive different quotations?
Even when two apartments have similar configurations, their final prices may differ because of:
For this reason, compare the total consideration value, not just the quoted rate per square foot.
Buyers may encounter different payment-plan descriptions while enquiring about Trump Tower Noida. These can include construction-linked plans, possession-linked structures and milestone-based payment schedules.
However, a payment-plan label alone does not tell you exactly when the money becomes payable. The actual schedule must specify the amount, due date or construction milestone, and the conditions attached to each instalment.
The following are common structures discussed in the market. They are included to help buyers understand the mathematics and should not be interpreted as confirmation that every option is currently available for every unit.
| Payment Plan | Booking / Initial Payment | During Construction | On Possession |
|---|---|---|---|
| Option 1: CLP | Initial instalment | CLI | Final instalment |
| Option 2: Easy EMI Scheme | 25% (₹5 Crore) | – | 75% (₹15 Crore) |
| Option 3: 30:40:30 Plan | 30% (₹6 Crore) | 40% (₹8 Crore) | 30% (₹6 Crore) |
1. Construction-Linked Payment Plan (CLP)
Under a construction-linked plan, payments are connected to specified stages of construction. The buyer pays instalments as the project progresses, subject to the agreed schedule and applicable regulations.
A typical structure may include payments at booking, agreement execution and subsequent construction milestones.
Why buyers consider it:
What to verify:
Do not assume that all construction-linked plans have the same percentages or milestone dates.
2. 25:75 Payment Structure
A 25:75 structure generally refers to 25% of the agreed consideration being paid initially and the remaining 75% becoming payable at a later defined stage, commonly described in marketing material as possession-linked.
For a property with a base consideration of ₹20 crore, the mathematical split would be:
Payment Component | Percentage | Illustrative Amount |
Initial payment | 25% | ₹5 crore |
Deferred payment | 75% | ₹15 crore |
Total base consideration | 100% | ₹20 crore |
This is a calculation example, not a confirmed Trump Tower Noida payment schedule.
Before selecting this structure, ask:
3. 30:40:30 Payment Structure
A 30:40:30 structure divides the agreed consideration into three parts. The exact meaning of each stage must be taken from the current written schedule.
For illustration, if the base consideration is ₹20 crore:
Stage | Percentage | Illustrative Amount |
Initial payment | 30% | ₹6 crore |
Second payment | 40% | ₹8 crore |
Final payment | 30% | ₹6 crore |
Total | 100% | ₹20 crore |
The second and final instalments must be mapped to the actual contractual milestones. Do not assume that the 40% is payable at a particular construction stage without checking the schedule.
Which payment plan is better?
There is no universally best payment plan. The right option depends on your liquidity, funding arrangements, risk tolerance and the exact terms offered.
Buyer Situation | What to Evaluate |
Buyer with substantial available funds | Compare any applicable upfront-payment benefit against the opportunity cost of locking in capital |
Buyer dependent on regular cash flow | Review instalment frequency and milestone-linked demands |
Buyer using a home loan | Check disbursement conditions and whether the bank's schedule aligns with developer demands |
Buyer planning to sell before possession | Review transfer restrictions, charges and outstanding payment obligations |
Buyer prioritising lower initial outflow | Compare the initial amount with the deferred liability and any associated conditions |
The key is not simply to choose the plan with the lowest initial payment. It is to understand the complete payment obligation from booking until possession.
A payment calculator can help buyers understand the financial implications of different payment structures before requesting a formal quotation.
The calculator below serves as an initial budgeting tool. It uses the property price entered by the user and does not include taxes, registration fees, floor-rise charges, or other expenses unless the user adds them separately.
Use the calculator to estimate:
Example: Payment calculation on a ₹20 crore residence
Payment Structure | Stage 1 | Stage 2 | Stage 3 |
25:75 | ₹5 Cr | — | ₹15 Cr |
30:40:30 | ₹6 Cr | ₹8 Cr | ₹6 Cr |
These calculations use a ₹20 crore base consideration purely for illustration. They do not represent a confirmed quote or the current payment terms of a specific unit.
Buyer takeaway: A lower initial payment does not necessarily mean a lower total cost. Always compare the complete schedule, including taxes, statutory charges and any financing-related conditions.
Buyers often make the common mistake of comparing properties solely based on their base price.
The final cost of the purchase can include several components beyond the apartment's base price. The applicable charges depend on the specific unit, the prevailing cost sheet, the mode of transaction, and current laws.
| Cost Component | What to Check |
| Base consideration | Agreed price of the apartment |
| Floor-rise charges | Whether a floor premium applies |
| View or location premium | Any additional amount for a particular orientation or position |
| GST | Applicability and calculation basis |
| Stamp duty and registration | Applicable charges at the time of registration |
| Parking | Number of spaces and whether the cost is included |
| Club or membership charges | Whether applicable and how they are calculated |
| IFMS or maintenance deposit | Amount, purpose and refund or adjustment conditions |
| Electricity and utility charges | Connection, meter or infrastructure charges, if applicable |
| Other contractual charges | Any additional amount listed in the cost sheet |
Do not assume that everything applies to every buyer. Ask for a written breakdown specifying which charges are included in the total price and which ones must be paid separately.
A practical way to compare two quotations
Suppose the base price appears identical in two quotations, but one includes certain charges while the other lists them separately. Comparing only the main price could lead to a wrong decision.
Before selecting a unit, ask for a cost sheet that clearly itemizes the following:
This gives you an accurate estimate of the cash required at each stage.
Before paying the EOI, booking amount, or any initial sum, seek written clarification on the points listed below.
1. Is the payment refundable?
Ask whether this amount can be refunded, adjusted against the sale price, or if any deductions will apply. Do not rely solely on verbal assurances.
2. What happens if the application is not accepted?
Check the refund timeline and the process for receiving the amount back.
3. Is the quoted price valid for a specific period?
Inquire about the date of the quotation and its validity period. Confirm whether the price is subject to change prior to allotment.
4. Is the unit number confirmed?
Verify the tower, floor, unit number, configuration and area mentioned in the booking documents.
5. Is the payment plan attached to the allotment documents?
The plan must be clearly outlined in written documents. Verbal information or graphics used for promotional purposes cannot replace the applicable schedule.
6. Are taxes and additional charges clearly explained?
Ask for a complete breakup rather than relying on a headline price.
7. What are the cancellation and transfer terms?
Understand deductions, timelines, transfer permissions and any applicable charges before committing.
8. Have you checked the RERA record?
Verify the project registration, promoter, approved details and declared completion date through the official UP-RERA portal.
Trump Tower Noida is being marketed as part of M3M The Cullinan II. In the project records available on the Uttar Pradesh Real Estate Regulatory Authority portal, the registered project is identified as M3M The Cullinan II.
| RERA Detail | Registered Information |
| Project name | M3M The Cullinan II |
| Registration number | UPRERAPRJ794824/10/2025 |
| Promoter | Lavish Buildmart Pvt. Ltd. |
| Registration date | 3 October 2025 |
| Declared completion date | 31 July 2030 |
| Registered address | Plot No. 1, Sector 94, Noida |
Official verification: UP-RERA Project Record
The projected completion date and the confirmed handover date for a specific apartment are not the same. Buyers should consult the sales agreement and current RERA details for the relevant phase.
The decision to purchase an ultra-luxury home should be based on the buyer's financial situation and the intended use of the property, rather than the common expectation of future price appreciation.
Buyers planning to live in the property should evaluate:
Investors should evaluate:
No property can guarantee a specific rate of price appreciation or rental yield. Any projected return should be treated merely as an estimate and evaluated based on actual costs and market conditions.
Various payment plan structures are available in the market, including construction-linked and percentage-based options. The applicable plan depends on the current offers and the specific unit selected. Before booking, request the latest schedule issued by the developer in writing.
The booking amount may vary depending on the unit and applicable offers. Do not assume that a fixed percentage, such as 10% or 25%, applies universally. Verify the exact amount and the terms regarding its refund or adjustment in the booking documents.
Trump Tower Noida Payment Plan & Complete Cost...
M3M Trump Tower Location & Connectivity: Secto...
M3M Mansion Construction Update: Sector 113 – Ho...
M3M Elie Saab Payment Plan: The Real Numbers, Hidd...
M3M Jewel Construction Update: Real Status & W...
M3M St. Andrews Sector 113: Location & Connect...
 Sector-9, Manesar, Gurugram
 2.5, 3 & 4 BHK Luxury Apartments
 1,080 sq. ft
 2.10 Cr*
 Sector-9, Manesar, Gurugram 2.5, 3 & 4 BHK Luxury Apartments 1,080 sq. ft 2.10 Cr*
 Sumit Chauhan / Real Estate Consultant